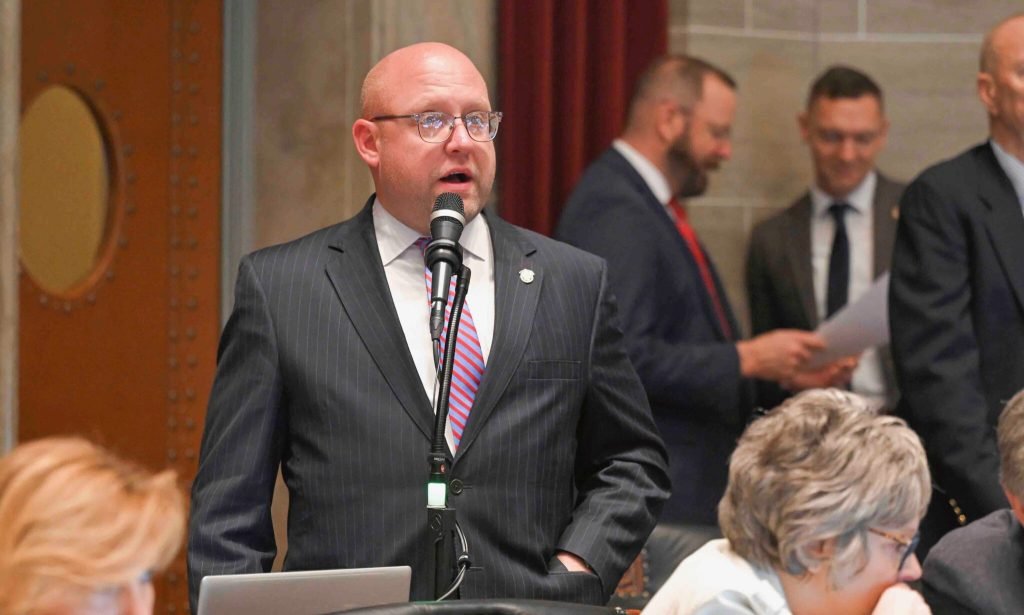
Missouri House Speaker Pro Tem Chad Perkins of Bowling Green speaks during debate on February 11, 2025. Photo: Tim Bommel/Missouri House Communications.
Missouri changed its individual income-tax treatment of capital gains beginning with tax year 2025. Under the current law, an individual may subtract 100% of income reported as a capital gain for federal income-tax purposes when calculating Missouri adjusted gross income.
This is a Missouri income-tax subtraction. It does not eliminate federal capital-gains tax, change the federal rules that determine whether a gain is taxable, or guarantee that every amount associated with an asset sale qualifies.
When the Missouri Capital-Gains Subtraction Began
The individual subtraction applies to Missouri tax years beginning on or after January 1, 2025. Eligible amounts are reported on the Missouri return filed for that tax year. The Missouri Department of Revenue’s tax-year guidance identifies the subtraction as effective January 1, 2025.
What Individuals May Subtract
Section 143.121 of the Revised Statutes of Missouri allows individuals to subtract 100% of income reported as a capital gain for federal income-tax purposes, to the extent that amount is included in federal adjusted gross income.
The Department of Revenue states that the subtraction may apply to federally reported capital gains from assets such as stocks, real estate, and cryptocurrency. The amount available on a Missouri return depends on how the gain is reported on the taxpayer’s federal return.
How the Subtraction Is Reported
The 2025 Missouri individual income-tax instructions direct taxpayers to report the eligible capital-gain amount on Form MO-A, Part 1, Line 18. The instructions tie the subtraction to the capital-gain amount reported on Federal Form 1040 or 1040-SR, Line 7a, and require the applicable federal return and schedules.
Capital losses and other federal reporting rules can affect the amount shown on the federal return. A 2026 Department of Revenue ruling confirmed that a taxpayer could not increase the Missouri subtraction by adding back capital losses that had already reduced the net gain reported federally.
Individuals and Corporations Follow Different Rules
The individual subtraction began with tax year 2025. The corporate provision has a separate trigger: it begins in the tax year after Missouri’s top individual income-tax rate reaches 4.5% or less. The Department of Revenue reported a 4.7% top individual rate for tax year 2025, so corporations were not eligible under that provision for 2025.
What This Can Mean When Real Estate Is Sold
A real-estate sale can produce a federal capital gain, but the result depends on factors such as the property’s adjusted basis, improvements, selling expenses, ownership, use of the property, and any applicable federal exclusion. Missouri’s subtraction generally begins with the capital-gain amount that reaches the federal return; it does not replace that federal calculation.
Before making a selling decision based on anticipated tax savings, property owners should review their circumstances with a qualified tax professional. Mavromatis Properties can help with the real-estate side of a planned sale, including preparation, market positioning, and the selling process, but does not provide tax or legal advice.
Related St. Louis Seller Resources
This article provides general information and is not tax, accounting, or legal advice. Tax laws and individual circumstances can change. Consult a qualified professional about your return and any proposed transaction.